Indonesian Capital Market Possesses Strong Fundamentals Amid MSCI Standalone Market Reclassification Threat

The Indonesian capital market is currently navigating a critical juncture following a momentous announcement by index provider Morgan Stanley Capital International (MSCI) regarding the potential downgrading of Indonesia’s market classification from an Emerging Market to a Standalone Market. This development has sent ripples through the domestic financial ecosystem, prompting high-level responses from government officials, market regulators, and key stakeholders. Amid growing concerns regarding foreign portfolio adjustments and global investor sentiment, the leadership of the House of Representatives (DPR) has stepped forward to reassure market participants, emphasizing that the intrinsic strength of Indonesia’s domestic economic fundamentals far outweighs external rating adjustments.
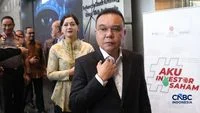
Sufmi Dasco Ahmad, a prominent leader and Deputy Speaker of the Indonesian House of Representatives (DPR), has voiced strong confidence in the resilience of the nation’s capital market. Responding directly to the turbulence sparked by the MSCI review, Dasco asserted that Indonesia possesses the capability to independently steer its financial course and determine its own market rating through the collective unity and resilience of local capital market participants.
Speaking through a public statement via his official social media channels, Dasco underscored that building a robust and unshakeable financial market requires unwavering solidarity among all stakeholders to confront various structural and external challenges, including evaluations by global index providers. "In our stock exchange, together we will build and determine our own rating. We unite, move, and fight. Towards a Winning Nation!" Dasco remarked, rallying domestic confidence against the backdrop of international regulatory scrutiny.
Understanding the MSCI Reclassification Threat: Background and Context
The catalyst for the current market anxiety stems from an official communication issued by MSCI, outlining a formal consultation proposal to alter the classification of Indonesian equities. Under the current framework, Indonesia is categorized as an Emerging Market, making it a staple component of widely tracked global benchmarks such as the MSCI Emerging Markets Index. This status ensures that trillions of dollars in passive and active global investment funds managed by institutional investors worldwide automatically allocate capital to Indonesian listed companies.
However, MSCI has signaled that Indonesia’s continued status as an Emerging Market may no longer accurately reflect the evolving realities, structural nuances, and regulatory dynamics of the domestic stock market. The global index provider’s review was triggered by persistent concerns raised by institutional investors regarding the overall investability of Indonesian equities. Specifically, market participants have pointed to challenges surrounding the transparency of corporate ownership structures and allegations of coordinated trading practices that could potentially distort fair price discovery.
To address these concerns and gather comprehensive feedback, MSCI initiated a formal consultation period with global market participants. According to the timeline outlined by the index provider, this extended consultation phase will allow stakeholders to submit feedback, data, and recommendations. MSCI has indicated that it may provide interim updates regarding market participants’ responses throughout the consultation window, with a definitive final decision scheduled to be announced no later than June 30, 2027.
Decoding the ‘Standalone Market’ Designation
The prospect of transitioning to a "Standalone Market" represents one of the most drastic classification shifts within the MSCI framework. Within global financial taxonomy, a standalone market status places a country outside the primary tiers of Developed Markets, Emerging Markets, and Frontier Markets.
The defining characteristic of a standalone market is precisely as the name implies: isolation from mainstream global equity indices. If Indonesia is ultimately reclassified into this category, Indonesian equities will be entirely removed from cornerstone benchmark portfolios such as the MSCI Emerging Markets Index and the MSCI Frontier Markets Index. While MSCI may theoretically continue to calculate individual indices for Indonesia on a standalone basis, these figures will no longer serve as mandatory reference portfolios for the vast majority of global asset managers, pension funds, and exchange-traded funds (ETFs).
The practical implications of such a downgrade could be profound. Historically, emerging market status acts as a powerful magnet for foreign institutional capital. When a nation loses this classification, passive funds tracking the benchmark are legally and operationally mandated to divest their holdings in that market to maintain index alignment. This can trigger substantial capital outflows, increased exchange rate volatility, and a temporary contraction in market liquidity, forcing domestic regulators and market operators to accelerate structural reforms to regain international credibility.
Chronology of Events and Official Review Timeline
The trajectory leading up to the 2027 decision involves a structured sequence of assessments, consultations, and potential remedial actions by Indonesian authorities:
- Mid-October 2026: MSCI officially releases a consultation proposal regarding the potential reclassification of the MSCI Indonesia Index from Emerging Market to Standalone Market status, citing investability, transparency, and market integrity concerns.
- Late October 2026: Domestic financial authorities, the Indonesia Stock Exchange (IDX), and high-ranking government figures, including DPR Deputy Speaker Sufmi Dasco Ahmad, publicly respond to the announcement, emphasizing domestic economic fundamentals and calling for unity among market participants.
- Late 2026 through Early 2027: An ongoing, multi-month consultation period takes place, during which MSCI engages with global institutional investors, local regulators, and market intermediaries to evaluate structural reforms and feedback.
- Mid-2027 (On or before June 30, 2027): MSCI is scheduled to issue its final, binding decision regarding the market classification of Indonesia, alongside any potential interim status reports during the consultation cycle.
Economic Implications and Structural Challenges
Financial analysts and market observers note that the MSCI warning serves as both a severe warning and an unexpected catalyst for deeper structural introspection within Indonesia’s financial sector. Over the past decade, the Indonesian capital market has witnessed remarkable growth, characterized by a surge in retail investor participation, numerous high-profile Initial Public Offerings (IPOs), and increasing digitization of trading platforms.
Despite these domestic achievements, global institutional standards place an exceptionally high premium on transparency, free-float liquidity, prevention of market manipulation, and accurate disclosure of ultimate beneficial ownership. The concerns raised by MSCI highlight persistent structural gaps that foreign investors view as friction points in their risk management frameworks. Issues related to concentrated shareholdings, low effective free-float liquidity for certain blue-chip counters, and regulatory enforcement against coordinated trading activities have long been debated within domestic financial circles.
The reaction from key political figures like Sufmi Dasco Ahmad reflects a broader national sentiment: while international index providers wield significant influence over global capital flows, the domestic economy’s underlying metrics—driven by robust GDP growth, controlled inflation, robust domestic consumption, and an expanding middle class—remain fundamentally sound. Proponents of this view argue that relying excessively on foreign index weightings diminishes the true potential of local capital, and that a localized focus could accelerate the development of a self-sustaining domestic institutional investor base comprising pension funds, insurance companies, and sovereign wealth initiatives.
Market Resilience and the Path Forward
As Indonesia braces for the culmination of the MSCI review process in mid-2027, financial regulators, including the Financial Services Authority (OJK) and the Indonesia Stock Exchange (IDX), face the dual mandate of protecting market integrity and engaging constructively with international stakeholders. Addressing the transparency and investability concerns raised by MSCI will require rigorous enforcement of disclosure rules, stricter monitoring of trading anomalies, and enhanced protection for minority shareholders.
At the same time, the rallying cry from legislative leaders underscores a strategic pivot toward self-reliance. By strengthening domestic market infrastructure, encouraging broader local institutional participation, and enhancing corporate governance standards across all listed entities, Indonesia aims to prove that its capital market is resilient enough to thrive under any classification framework. Whether MSCI ultimately proceeds with the standalone reclassification or decides to maintain the status quo following remedial regulatory actions, the ongoing debate marks a defining chapter in the maturation of Indonesia’s financial markets on the global stage.